Skip to content

A 90-minute protection-planning book for business owners

Family.Business.Assets.Income.

Proximity does not provide protection.

You can know every account, call every advisor, and be the first person everyone reaches when something goes wrong. None of that automatically means the people and responsibilities you care about will keep working without you.

This book gives you a four-part way to see the gaps, understand what each professional is handling, and know what must keep working when you cannot personally hold everything together.

Reading time
90 minutes
Price
$10
Designed for
One sitting

Cover coming soon

Robbie Poe

Final cover artwork is in development.

The owner’s blind spot

You may already have all the right people. And still not have a plan.

Most owners are close to everything they have built. We know the customers. We recognize the accounts. We can call the CPA, find the insurance policy, and pull up the estate documents.

That closeness feels like visibility. Visibility feels like control. And after a while, control starts to feel a lot like protection.

Proximity creates familiarity. It does not create legal authority, ownership, access, insurance coverage, succession, documentation, or coordination.

Your attorney may be doing excellent work. So may your CPA, insurance professional, and financial advisor. The gap appears when no one is responsible for seeing how one decision affects all four parts of your life.

A quick pressure test

Seven questions that get uncomfortable fast.

These questions are boring right up until the day they are not.

  1. 01

    If you could not sign tomorrow, who could legally act?

  2. 02

    Who owns each important asset on paper, not merely in your head?

  3. 03

    Can the right person reach the right account without pretending to be you?

  4. 04

    Does your trust actually own what you think it owns?

  5. 05

    Does your company behave like a genuinely separate company?

  6. 06

    Does your insurance match the risks you actually carry?

  7. 07

    Which lawful tax choices close before filing season begins?

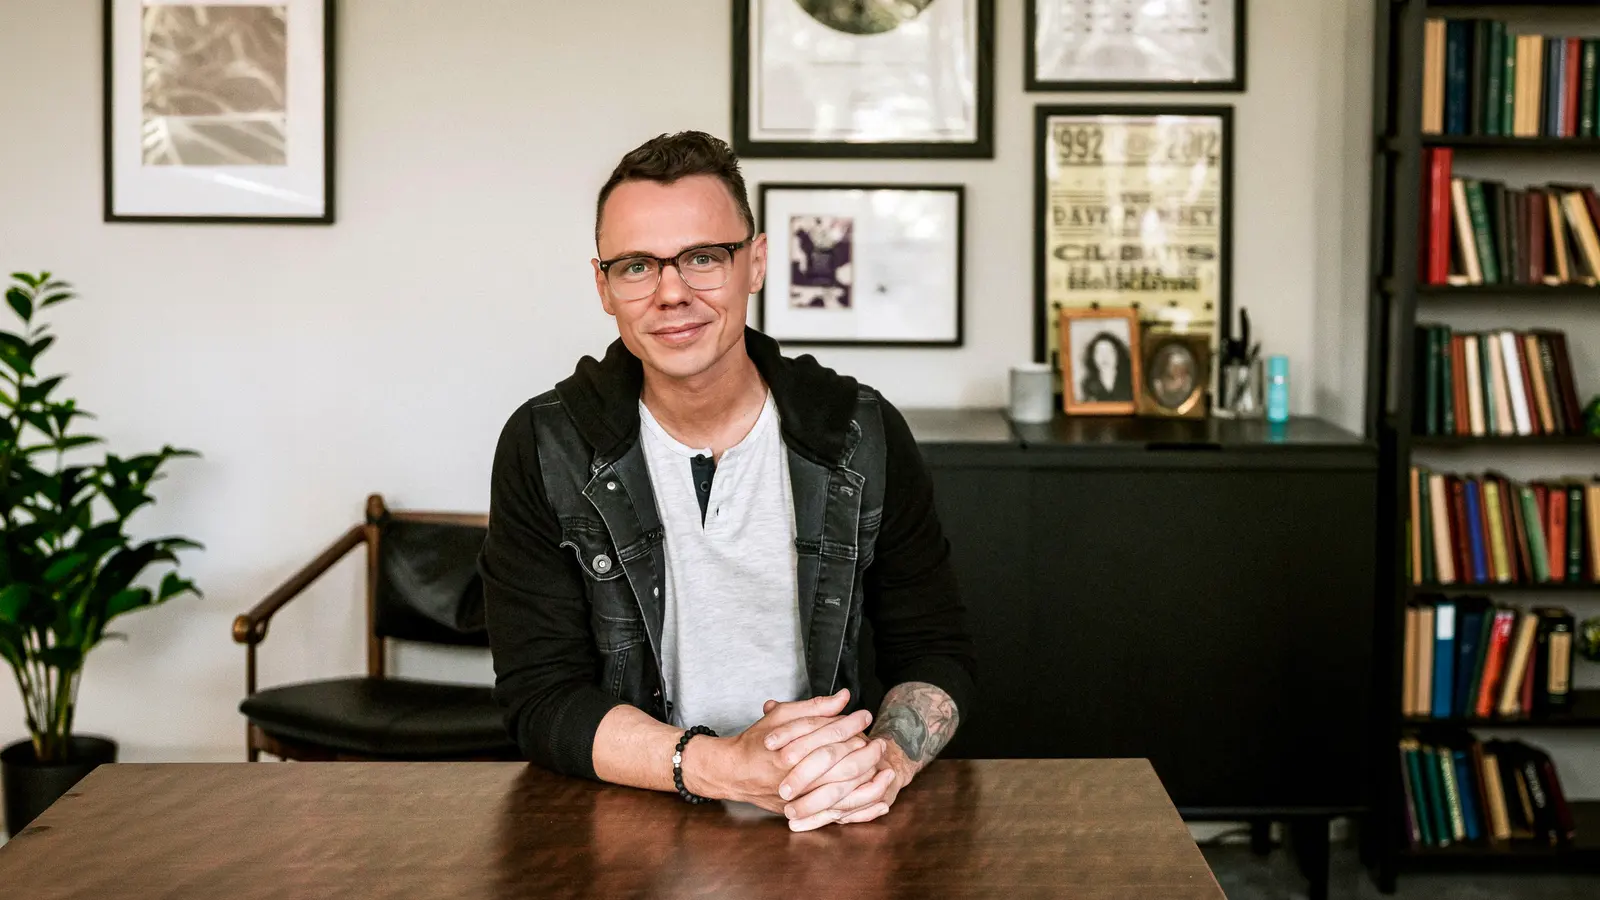
Robbie Poe seated at a table in his office

Written owner to owner

I wrote the book I needed before the subpoena arrived.

A lawsuit involving a former business partner reached for everyone it could. I had the LLC. I had insurance. I had professionals. I thought my family, business, assets, and income were well protected.

What I did not have was cohesion.

That experience changed the way I look at owner protection. I assembled the right professionals, built the framework behind this book, and started helping other owners see the whole picture before a hard day forces the issue.

I want to be clear about why I wrote this: my goal is for you to hire me, or someone genuinely qualified to do this work, to build your protection plan. I would rather say that now than disguise the book as something neutral.

I am not an attorney, CPA, financial advisor, or insurance broker. My role is to start with the owner’s complete responsibility set, help build the blueprint, find the unanswered decisions, connect the qualified specialists, and keep the work moving through implementation and maintenance.
What the missing pieces cost

The gap appears at the handoff.

The documents may exist. The professionals may be excellent. The problem appears when authority, ownership, access, insurance, succession, and timing do not meet in the same real-world moment.

These are hypothetical illustrations, not predictions. Outcomes depend on the owner’s facts, documents, jurisdiction, insurance, and timing.

Family

Elena’s spouse has every password—and no authority.

A successful HVAC owner suffers a sudden stroke. Her spouse knows where the accounts are but cannot legally make the decisions. Payroll, banking, ownership, and family income begin to stall together.

Business

Andre owns everything directly.

His operating company, building, and minority interests all sit in his name. When a personal judgment arrives, what looked like one portfolio becomes an emergency asset-by-asset negotiation over control, access, and family income.

Assets

Melissa has the trust and the LLCs.

But a rental remains titled personally, the umbrella policy was never updated, an old beneficiary remains on file, and her spouse cannot find the documents. A tenant injury and medical emergency expose every disconnected piece at once.

Income

Carlos gets an accurate return.

He waits until March after his best year to ask what he could have done. The filing is correct. The choices, implementation steps, and documentation windows that might have changed the year are already closed.

Four responsibilities. One chain reaction.

A problem rarely stays where it begins.

A business problem becomes an income problem. An ownership problem becomes a family problem. An access problem can make valuable assets useless at the moment they are needed most. These are not four departments. They are four responsibilities.

A common path of value

Business → Income → Assets → Family

The planning lens

Family → Business + Assets + Income

  1. 01

    Family

    Passwords are not authority.

    The people who inherit the consequences of your decisions and preparation. Family is why the other three responsibilities matter. You will see why incapacity, guardianship, beneficiary coordination, succession, and trust funding have to work as one system.

  2. 02

    Business

    An entity is one layer, not the whole plan.

    The economic engine you built creates income, concentrates risk, carries obligations, and may be the largest illiquid asset your family is counting on. You will connect ownership, governance, separation, contracts, insurance, continuity, and personal events to control of the company.

  3. 03

    Assets

    A list is not a protection strategy.

    Assets are stored choices. They create future options only when ownership, control, liability, insurance, access, taxation, and succession have been handled deliberately. The book helps you pressure-test what you own instead of merely listing it.

  4. 04

    Income

    Filing is not planning.

    The flow that keeps everything else alive becomes exposed when the owner cannot work, decide, sign, sell, or gain access. You will see why lawful choices have decision windows, why documentation matters, and why the smallest tax bill is not always the best owner-level outcome.

The plan you can finally see

Four parts. None of them works alone.

These are not four unrelated products. They are four coordinated parts of one owner-level plan. The final design depends on your facts, jurisdiction, goals, and qualified professionals.

  1. 01

    A trust-centric estate plan

    Coordinates authority, access, incapacity, guardianship, succession, beneficiaries, and actual trust funding. Signing a trust does not mean the trust has been funded.

  2. 02

    A disregarded holding company

    Creates a deliberate ownership and governance layer for appropriate interests or assets when the owner’s facts support it. “Disregarded” can describe federal tax treatment. It does not mean legally nonexistent or automatically protected.

  3. 03

    An asset organization strategy

    Makes an asset-by-asset decision about ownership, control, liability, insurance, access, taxation, and succession. A net-worth spreadsheet tells you what exists. It does not tell you whether it will work when you need it.

  4. 04

    Tax reduction tools

    Identify lawful strategies, elections, benefits, structures, and timing choices while their decision windows remain open. A tax return records the year you already chose.

The concepts beneath the documents

Having the piece is not the same as having the protection.

Paper becomes useful when it describes something real and the real-world behavior matches it. The book gives you plain language for the concepts that keep a plan from becoming another stack of documents that only looks complete.

Ownership
The name and legal capacity the law recognizes, not simply who paid for or uses something.
Control
The power to decide. Control can be separated from ownership, so a plan must answer both questions.
Access
The practical ability to reach money, records, accounts, and authority at the moment they are needed.
Separation
The repeated behavior that makes a legal boundary believable after the formation paperwork is filed.
Funding
Connecting property and accounts to the structure that is supposed to govern them in real life.
Timing
Making choices while they are still available. An accurate filing cannot recreate an expired decision window.

Concern is not equipment

A sword, a shield, and armor.

The metaphor is not a promise that no threat will ever land. It is a simple way to remember what real preparedness requires.

01

The sword

The binder.

The plan, documents, decisions, evidence, review dates, and professional contacts. It answers a challenge with organized proof.

02

The shield

The protection plan.

The coordinated design connecting ownership, authority, liability, insurance, access, succession, and taxation.

03

The armor

The routines.

The recurring work that keeps trusts funded, entities separate, assets titled and insured, access current, and tax choices documented on time.

The sword contains the proof. The shield supplies the design. The armor keeps the system ready.

Prepared is different from untouchable

This book will not turn you into your own attorney.

It will help you see the whole responsibility set, give you language for the gaps, show you what coordinated planning should look like, and help you ask better questions of the people around you.

It will not prescribe one structure for every owner, replace qualified attorneys, CPAs, insurance, benefits, or investment professionals, or promise immunity from claims, tax, loss, incapacity, or conflict.

Life is too unpredictable and every owner’s facts are too different for honest people to make those promises. The goal is not invincibility. It is deliberate preparation.

Educational only; not individualized legal, tax, insurance, investment, accounting, or financial advice.

Questions before you read

The honest answers.

I already have an attorney, CPA, insurance agent, and financial advisor. Why read this?

The missing element may not be another professional. It may be one owner-centered plan connecting what each professional sees. The book helps you recognize whether that coordination actually exists.

Is this a do-it-yourself legal or tax manual?

No. It teaches the framework, language, questions, and planning standard. The correct documents, ownership, elections, insurance, and implementation depend on your facts, goals, jurisdiction, and qualified professionals.

Does every owner need the same trust, holding company, or tax strategy?

No. The book explains a four-part planning architecture. The design and suitability of any particular structure or tool are fact-specific. Complexity should have to earn its place.

Will this make my assets untouchable?

No. The book rejects promises of being bulletproof, untouchable, or fully protected. Its goal is deliberate preparation, organized evidence, professional coordination, and continuing maintenance.

Is this only for large companies?

No. It is for owners whose business supports the household, holds meaningful family wealth, or carries the owner’s identity and future. A solo owner and a staffed company simply require different levels of analysis.

Is the book a sales pitch?

It has an openly disclosed commercial purpose. My goal is for you to hire me, or someone genuinely qualified to perform the same coordinating role, to build and maintain your protection plan. I would rather say that plainly than hide it in the final pages.

How long is it, how much is it, and when can I read it?

The book is designed to be read in roughly 90 minutes, in one sitting, for $10. It is coming soon. Use the link below to ask when pre-ordering opens.

Coming soon

Your family, business, assets, and income deserve more than your proximity.

Read it in one sitting. See the whole picture differently. Then decide what needs to happen next.

90 minutes. $10. One sitting.

You’ve built something worth protecting.

You'll never regret making sure that your family, business, assets, and income are protected.

Work With Me